

For most of the past five centuries, finance was attached to production. Money was invested in goods and services, which generated returns, which were then reinvested. Capital had to pass through production (through the exploitation of labour power and the sale of commodities) before it returned as more money. Financial speculation existed, of course—it is as old as the Venetian bankers of the thirteenth century. But it was an appendix; a parasite, perhaps, but one that fed off a host.
Over the last half a century that relationship has reversed. Today, especially in the United States and across the West, financial capital no longer sits at the top of a pyramid built on factories, shops, and wages. The pyramid has been turned upside down. Financial markets—the abstract, obscure trade in securities, derivatives, and repurchase agreements—are now the foundation on which economic life (production, services, consumption) rests. Money begets money without having to pass through circulation, and the reproduction of society is dragged along behind.
This is why financial crises are now economic crises tout court. When the markets seize up, credit freezes. When credit freezes, businesses cannot pay their workers. When workers go unpaid, they stop buying goods. When goods go unsold, more businesses fail. The point to note here is that the real economy does not stand on its own and wait for finance to recover. It is dependent on finance, like a terminal patient on life support. The market crashes of the past two decades are not accidents that happened just to the financial sphere: they are crises in the reproduction of the financialised world itself, where entire populations are treated as collateral.
This is the form of the contradiction that defines our time. A system supposed to allocate capital to productive uses has morphed into a system in which productive activity must be continuously subsidised by financial expansion. When that expansion stalls or convulses, the damage reaches deep into the lives of ordinary people: their jobs, savings, and retirement schemes.
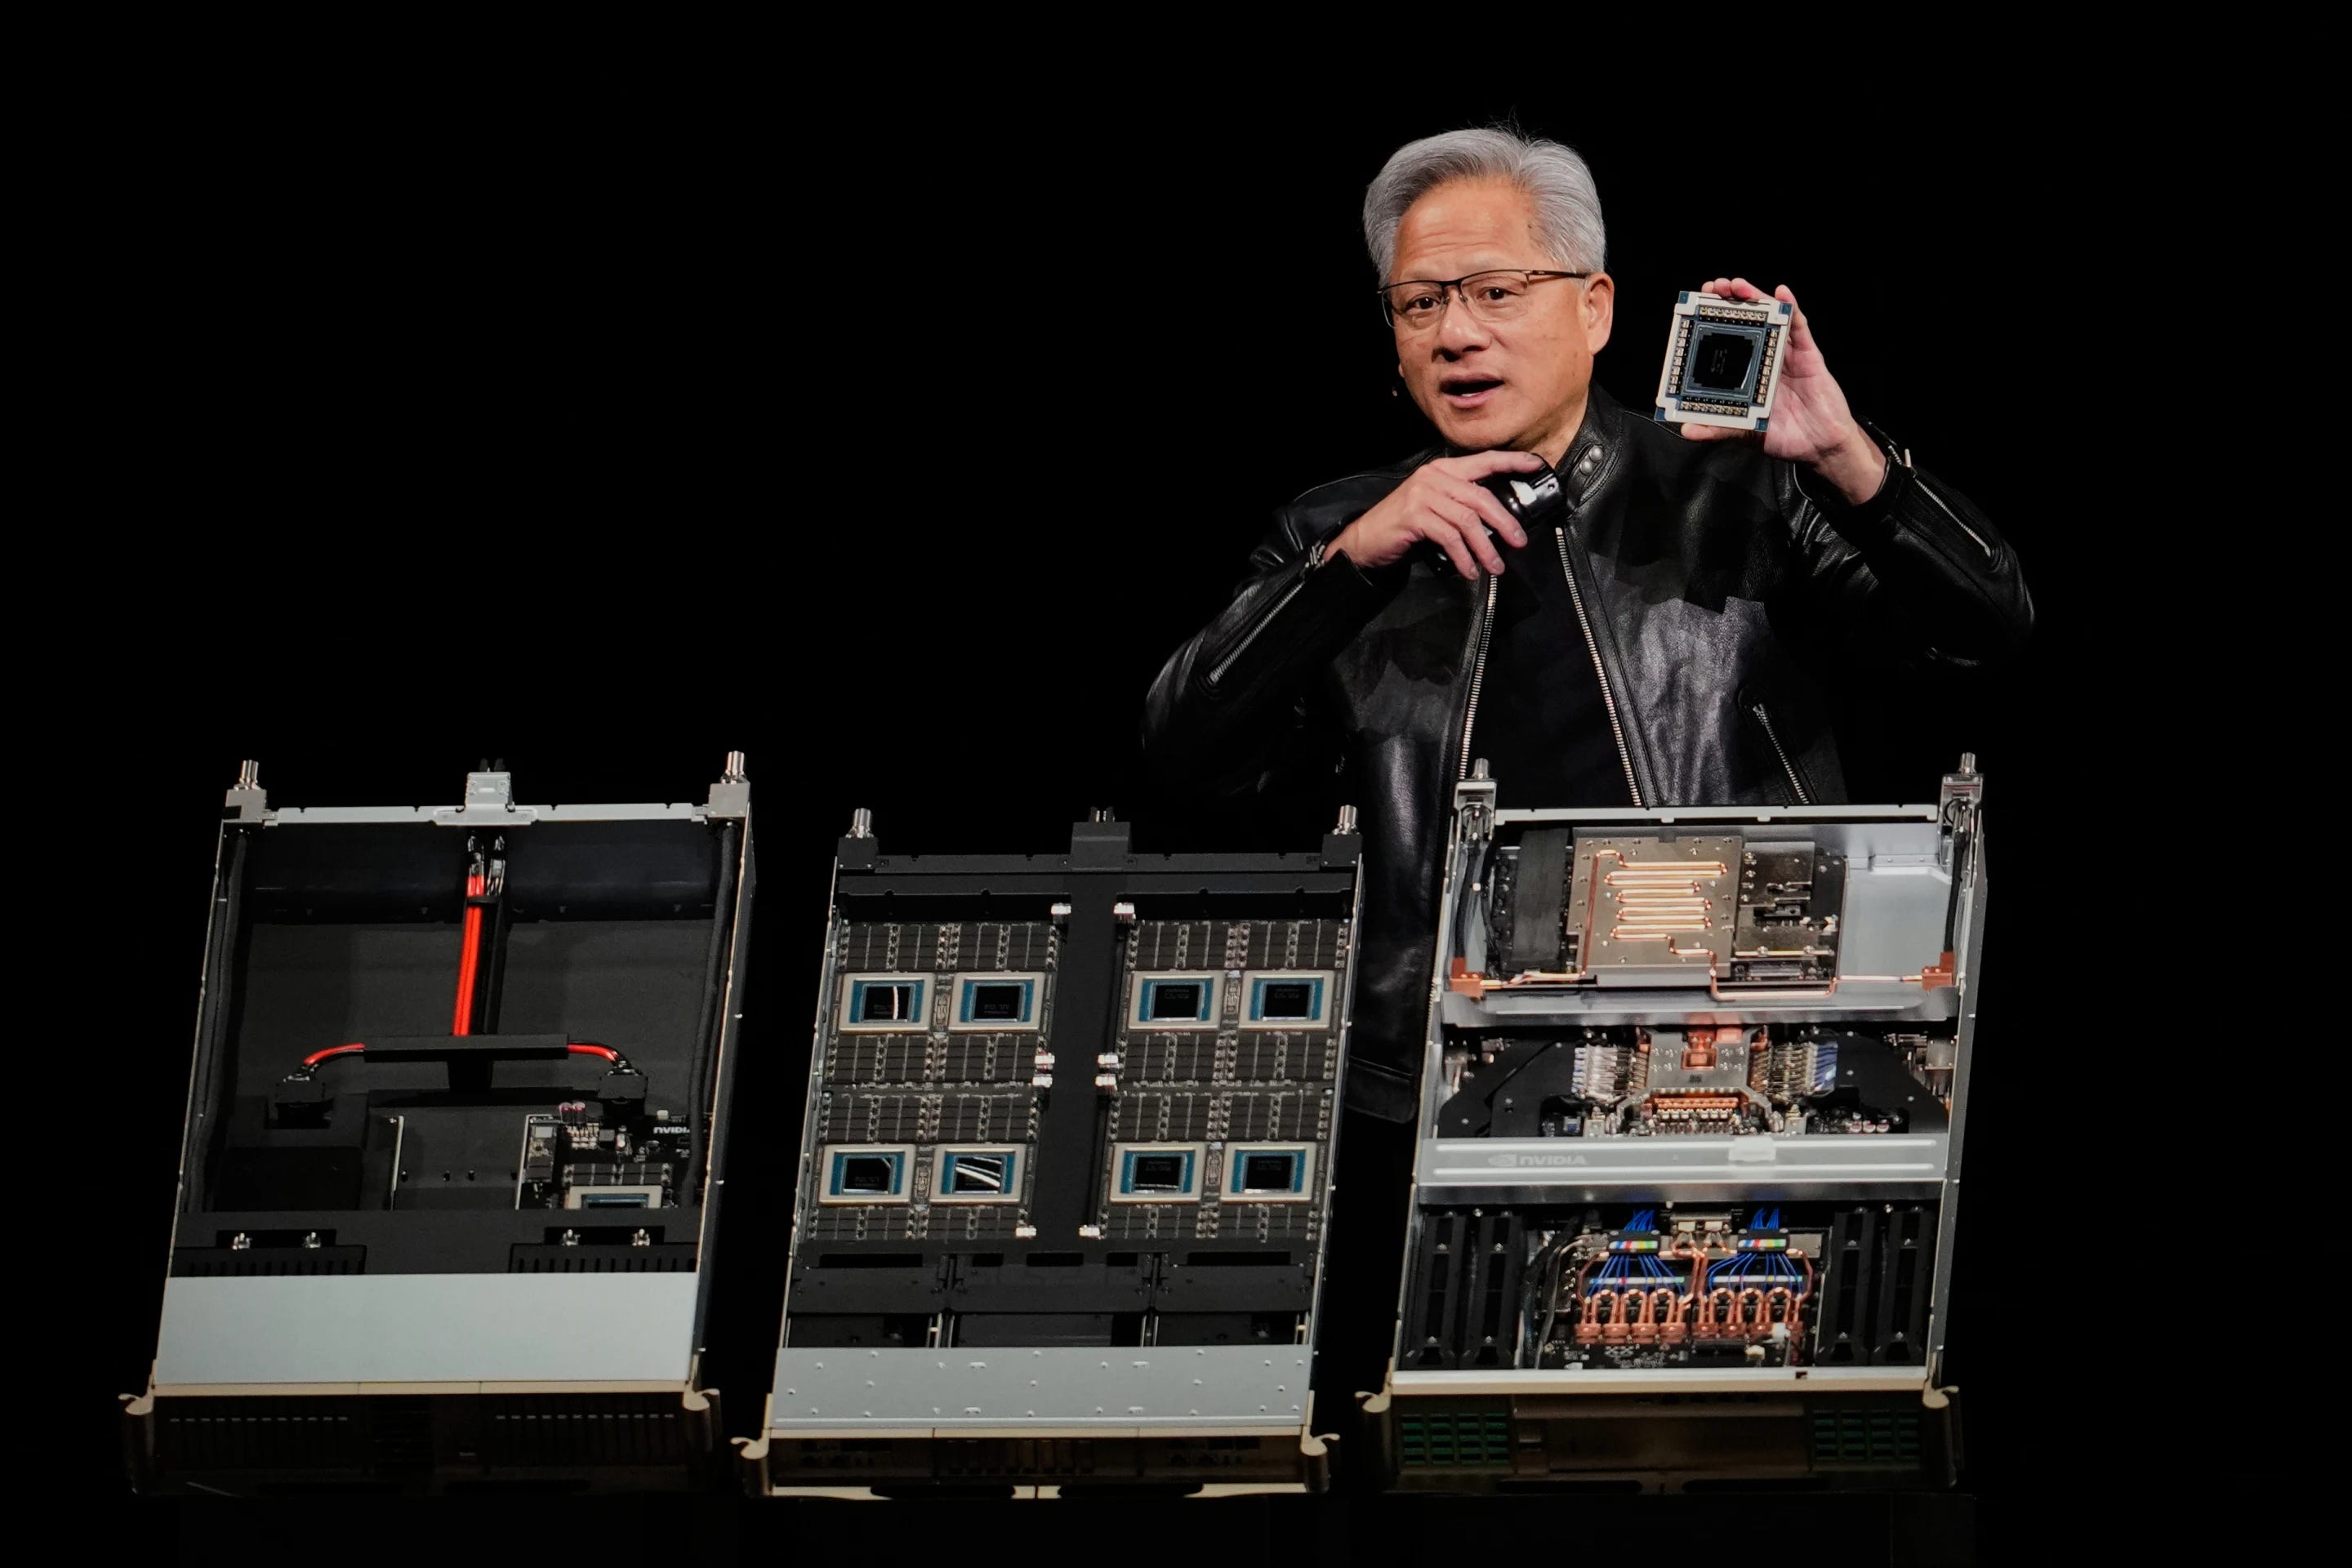
Today, Nvidia’s share buyback programme offers perhaps the purest illustration of this logic; a case study in how financial engineering at the top of the inverted pyramid determines whether the people at the bottom can count on the future they were promised.
The pizza problem
When a company like Nvidia buys back its own shares, it is essentially taking stock off the market. This means that fewer shares are left floating around for investors to buy. Why does this matter? Because a company’s earnings-per-share is calculated by dividing its profits by the number of shares in existence. If you shrink the number of shares, the same profit suddenly looks bigger on paper, even if the business itself is not actually doing any better.
Think of the company’s profit as one pizza, shared among its stockholders. If the company buys back some shares, fewer shares are left to represent claims on that profit. The slice assigned to each remaining share gets bigger, but the pizza—and the company’s profit—hasn’t grown. A higher earnings-per-share figure doesn’t, by itself, mean the business is doing better or that the stock is worth more.
Now, Nvidia is doing this on an extraordinary scale. In September 2026, the board added $150 billion to its existing authorization, bringing the remaining amount available for repurchases to $235 billion. This is the largest such programme in history, dwarfing Apple’s previous record of 110 billion. And because the company’s share price is already based on the assumption that it will keep growing explosively for years to come, this relentless buying of its own stock works like a safety net under the price.
Where the money comes from
All of this depends on one thing: Nvidia bringing in enormous amounts of cash. In its 2026 financial year, the company generated around 96.7 billion dollars in free cash flow (money left over after paying its bills and investing in the business). That is an astonishing sum, and it rests on a near-monopoly in the specialised chips that power artificial intelligence in data centres.
But here is the problem. A huge chunk of that money comes from just a handful of customers. In the first half of its 2027 financial year, Nvidia’s three biggest customers—giant tech companies, not ordinary retail shoppers—accounted for 44 per cent of its revenue. If you include money owed to Nvidia but not yet paid, the top five customers made up 70 per cent. In the previous year, just two customers alone were responsible for more than a third of everything Nvidia sold.
Imagine a shop where three people buy almost half of everything on the shelves. If even one of them stops spending, the shop is in serious trouble. That is the situation Nvidia is in. Its entire buyback programme, and the share price it supports, depends on a very small number of very large companies continuing to spend colossal sums on AI infrastructure. If they slow down—if the AI furore simply fades—the cash dries up, and the buyback-related safety net disappears.
There is a second layer to this circularity. Apart from selling chips into the AI boom, Nvidia is pre-emptively investing in the ecosystem that buys them. By April 2026 its stakes in other businesses had reached 42 billion dollars, nearly double the previous year, including holdings in OpenAI and Anthropic. And this goes well beyond equity ownership. To keep demand for its hardware flowing, Nvidia has extended financing guarantees to shore up its customers’ credit lines—and has explored commitments of up to 250 billion dollars, later scaled back to under 120 billion, to support OpenAI’s expansion. (Incidentally, this retreat was not a change of heart, but early signs of structural friction. Even a near-monopolist like Nvidia is beginning to confront the regulatory limits and balance-sheet strains of acting as its own primary customer.) Add a 50-billion-dollar lease for a 1-gigawatt data centre in Texas, which will host its own hardware, and it should be clear that the chipmaker is evolving from a component manufacturer into the foundational operator and landlord of modern artificial intelligence.
But Nvidia’s expanding role in financing AI infrastructure raises a further question: will the companies building it earn enough to justify the cost? Goldman Sachs estimates that six major cloud and technology companies would need to generate $1.42 trillion in revenue from AI between 2028 and 2030 simply to earn a 15% return on their investment. Even to cover depreciation and operating costs, they would need about $920 billion.
Meanwhile, the commitments to build AI infrastructure are reaching trillions of dollars. The unresolved issue is whether the businesses buying Nvidia’s chips can turn that into enough revenue to pay for the vast infrastructure they are building. As Apollo’s Torsten Slok notes, analysts expect tech companies’ cash flow to more than double, while analysts covering the companies that buy their products expect much smaller increases: “Both cannot be right at the same time.” In truth, both sides of that contradiction share a single premise: that the future (demand, returns, productivity gains) will arrive on schedule, even though the present shows no sign of it.
The circle runs through your pension
What I’ve described above is not a literal circle where dollars go out and come straight back. It is, essentially, what used to be called “vendor financing”: a company helping its customers afford its own products. During the late 1990s dot-com boom, Cisco Systems did something very similar. It arranged financing for customers (highly leveraged startups) to buy its networking equipment, which propped up its sales and rocketed its share price—until the bubble burst and the stock collapsed. As many commentators have noticed, the pattern is back, dressed up in AI. While the comparison might not be exact, the underlying question returns: how much of a boom’s demand is being sustained by the same financial system that profits from the boom? While AI enthusiasts argue that GPUs represent real technological value, Cisco’s networking hardware was equally essential to the early internet. The issue, here, isn’t whether the tech works, but whether financialized demand can fabricate economic utility where none yet exists.
This is no longer confined to Nvidia’s own buybacks. Elon Musk’s SpaceX is reportedly seeking 40 billion dollars in debt to buy Nvidia chips—and Nvidia owns a stake in SpaceX. Once again, the supplier is helping to finance the customer’s purchase of the supplier’s product. And here’s the catch: the bonds that fund this will be sold to insurers and pension funds, because SpaceX’s investment-grade rating opens the door to them. The same savings pool that owns Nvidia through an index fund can also end up lending to SpaceX—the company buying Nvidia’s chips. Which means that the circle does not stay on Wall Street, but reaches into retirement savings—and not by accident. Pension funds are required, either by law or by their own rules, to track the major stock market indices. They do not choose to hold Nvidia; they have to.
That obligation now runs through a single stock: as of 10 October, Nvidia alone accounts for 8.24 per cent of the SPDR S&P 500 ETF and 8.08 per cent of Vanguard’s VOO. These two funds hold over $1.7 trillion in combined assets and are the primary engines of everyday retirement accounts. Because they must strictly mimic the S&P 500, any new cash entering them triggers an “automatic pump”: their algorithms are legally forced to buy Nvidia shares in exact proportion to its weight, driving up its price and increasing its index dominance in a continuous, self-reinforcing loop.
Together with Apple and Microsoft, Nvidia now makes up more than 21 per cent of the S&P 500—the highest concentration in the index’s history. Globally, Nvidia and Apple together carry a combined 9.95 per cent weight in the MSCI World Index, more than every company in the UK, France, and Canada combined.
Norway’s $2.3 trillion Government Pension Fund Global—the largest retirement pool in the world—now carries Nvidia as its single largest equity holding. The same pattern repeats across Britain, Canada, most EU countries, and the United States. The financial sphere has decided what the real economy’s retirement savings must own, and at whatever price the loop produces.
No exit?
This is the circularity that should concern us:
1. Nvidia’s money helps its customers afford its products;
2. Those purchases become Nvidia’s revenue;
3. That revenue funds buybacks and investments in other companies;
4. Those buybacks and investments support the share price;
5. The share price is what pension funds are forced to track, whether they like it or not.
If the loop breaks—if Microsoft, Alphabet, or Meta cut back their spending on AI infrastructure because the returns are not what they hoped—then the cash dries up, the buybacks become impossible to sustain, and the share price falls. Because Nvidia is so deeply woven into every major index, that fall would drag down the entire market, and the losses would land on retirement portfolios around the world. At that point, hundreds of billions of dollars spent buying back shares at peak prices would turn out to have been value destroyed, not value stored. And the people who would pay for it are not Nvidia’s executives, but the savers whose pension funds were locked into the trade by design.
This is what it means to live in a system where M-M’ (Money generating Money) has replaced M-C-M’ (Money invested in Production to generate Money) as its engine. While animated by the same greed, the financial sphere does not merely sit alongside real socioeconomic life—it sustains it. And when the financial sphere convulses, real lives convulse with it.
In the early 1970s, at the dawn of the “neoliberal revolution” that financialised the world, French psychoanalyst Jacques Lacan described the “discourse of the capitalist” as a discourse that spins without friction, without a break, without a point at which it is forced to confront what it lacks and represses. He represented it as a “horizontal eight”—the figure that emerges when the four terms of the discourse are arranged so that no point of impossibility interrupts the circuit; the symbol of the infinite, of a movement that feeds itself and never stops.
And the reason it “believes” it never stops is that the subject—the only place from which a break could be made—has been foreclosed, radically excluded. There is no addressee in this discourse, no one to whom the social bond could be asked to justify itself. Economic power is everywhere, and therefore nowhere in particular: it cannot be isolated, located, or addressed. You are free to argue about anything in a modern, liberal democratic setting—indeed, you are told that this is what freedom means—but the logic of capital itself is not up for debate; not because it is censored, but because any debate already presupposes it. Political subjectivities have become ancillary, when not openly enslaved. As an unquestionable premise, financialised capital closes every potential political opening. It does not answer any question. Instead, it removes the place from which a question could be asked.
In the age of the AI bubble, this logic reigns supreme. There is no natural point of interruption in the loop—which is why the interruptions must be manufactured and then “managed.” For this reason, the next emergency is not so much a failure of the system but the system’s modus operandi, the way it continues by other means. Here, then, is the cul-de-sac where we’ve landed by following the logic of capital. If we don’t keep the financial structure doped—if we let the markets find their real level—the outcome will wipe out most people attached to it. If we keep it doped, it simply bleeds us slowly, a death by a thousand cuts. Do we still have a choice? If so, which one? If the only choice is between keeping the finance doped and letting it collapse, what kind of choice is that?