

I have been saying this for a long time: the house of cards desperately seeks another emergency-justified round of (inflationary) QE. It now looks like the time for serious rehearsals has arrived. The financial, political, and infrastructural foundations of the current accumulation model are visibly beginning to fray.
Let’s start with Paraguay. Ueno Bank, a major digital lender, collapsed after the country’s central bank found it had breached minimum solvency requirements. Nearly 3 million people—around 60% of the adult population—suddenly found their accounts frozen, apps and cards useless, and pensions blocked. Mass protests and riots erupted. This is what financial “normality” looks like when the plumbing actually fails. No, it’s not a Hollywood movie; it’s ordinary people being unable to access the money that organises their lives.
In the political aftermath, President Santiago Peña—a right-wing economist and close Trump ally whose past business links to Ueno Bank were central to the crisis—resigned and then was impeached. In a matter of hours, a national banking failure turned into a constitutional crisis. The lesson is that in a financially addicted society, a bank’s collapse is never just a bank’s collapse: it destabilises the foundations of social life, from payments and pensions to trust and state legitimacy itself.
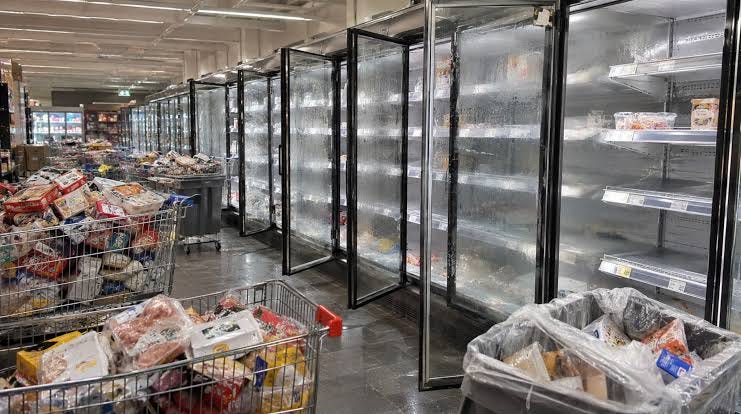
Europe, meanwhile, provided its own rehearsal in vulnerability. On 5 November, at least 27 passenger flights received bomb threats, triggering diversion and various kinds of disruptions. Authorities described these scares as hoaxes, since no devices were found. In the same week, hackers remotely manipulated supermarket refrigeration systems across several European countries, switching them into defrost mode and causing widespread food spoilage. French blood banks were also reported to have been targeted.
No attribution has been established. Yet the implicit—sometimes explicit—mainstream message is, of course, that the long hand of Russia is behind it all. But surely there is another, more systemic connection worth examining: the one between a debt-saturated, financially driven mode of production and the intrinsic fragility of critical infrastructure. The point is that the latter can be disrupted without tanks and missiles. In a system that has optimised everything for speed, efficiency, and financial gain, a few keystrokes can generate very useful chaos.
It would seem that the AI bubble is where these vulnerabilities increasingly converge. According to the latest financial filings and market estimates, Alphabet, Meta, Microsoft, Amazon, Oracle, Nvidia, Broadcom, and SpaceX together carry more than $4.11 trillion in off-balance-sheet commitments (purchase obligations, signed leases, guarantees tied to data centres, chips, energy, and cloud capacity). This is more insidious than ordinary balance-sheet debt. It is, in effect, a mountain of future claims: payments that accounting frameworks do not consistently expose and that markets have not yet fully priced.
Alphabet alone has crossed the trillion-dollar Rubicon. Its latest mandatory filing puts future energy and data-centre payments above $1 trillion: $924.4 billion in off-balance-sheet purchase commitments, plus $130.5 billion in leases not yet commenced. Meta is close behind, with roughly $825 billion in disclosed commitments; its non-cancellable purchase commitments jumped from $349 billion to $455 billion, while not-yet-active leases rose from $279 billion to $356 billion—all in a single quarter.
Harmless “investments”? Hardly. These are contractual claims on future cash flow—claims that must be financed, refinanced, or, eventually, paid. The madness is that they rest on the delusional assumption that AI will generate returns vast enough to justify the most expensive infrastructure boom in history. But the market may finally have started doing the maths. A coordinated repricing? Too soon to say with certainty. For now, it is enough to note that, today, the Nasdaq Composite closed down 5.52%.
The other issue concerns ratings. S&P counts off-balance-sheet leases as debt, while Moody’s and Fitch take a looser approach. So, depending on who’s doing the counting, the same corporate empire can look far more (or far less) leveraged. If the agencies ever standardise their treatment of these instruments, the investment-grade façade holding the financing loop together could weaken considerably. S&P has already cut Meta’s outlook to negative (while keeping its AA rating) over AI capex, negative free cash flow, and rising future lease obligations.
In short, this is how financial pressure becomes a systemic problem. AI infrastructure runs on continuous access to debt and investor confidence. If credit conditions tighten, the cost of the buildout climbs just as doubts about AI profitability deepen: the perfect shitstorm.
The wider implications are fairly obvious. The next monetary rescue will not be sold as a bailout for speculative capital. Instead, it will be framed as a necessary means to protect pensions, savings, access to money and food, national security, or even “AI leadership.” The crisis will go by some other name, while the liquidity will flow to the same institutions that created the critical exposure.
So yes: the system desperately needs another rescue. The only question, I think, is which emergency will be used to justify it—and how effectively those emergency powers will slow money velocity, clearing the way for fresh monetary expansion to reach the usual suspects. The constant inflation of financial assets requires the deflation of life.